U.S. Defense Exports: Maintaining Momentum in Turbulent Times
Last updated 06:20 AM EDT • Read time: 7m
Four years of taxing conflict in Ukraine, growing competition from international arms suppliers, and Trump Administration reforms are driving needed change to the United States’ defense exports process. Strained capacity, changing requirements, and more spending across defense markets in Europe, the Middle East, and Asia have all laid the groundwork for a more energetic, consistent, and productive approach to U.S. defense exports. But the Trump Administration’s haphazard approach to alliance management, our partners’ national security needs, and business practices could slow that progress.
In past decades, U.S. defense exports, both via the government-to-government foreign military sales (FMS) process and the company-driven direct commercial sales (DCS) channel, have often been the ugly stepchild of the Department of War (DOW) acquisition process. While exports are profitable for industry, desired by allies, and critical for alliance capabilities and U.S. national security, they were often viewed as burdensome afterthoughts or distractions in a defense acquisition ecosystem focused on serving the immediate U.S. customer. The harsh realities of sustained combat in Europe, increasingly capable global defense industry competitors, and a reform-minded Administration, however, are shaking up this calculus.
Russian aggression in Ukraine has focused U.S. and allied policymakers on the need for increased military capabilities and stockpiles, driving increased spending and opportunities for global defense companies, notably those in the U.S. The importance of interoperability amongst allies has eroded fragmented and parochial defense investment philosophies of the past. Here too, widely deployed U.S. defense offerings are perfectly suited to address these challenges.
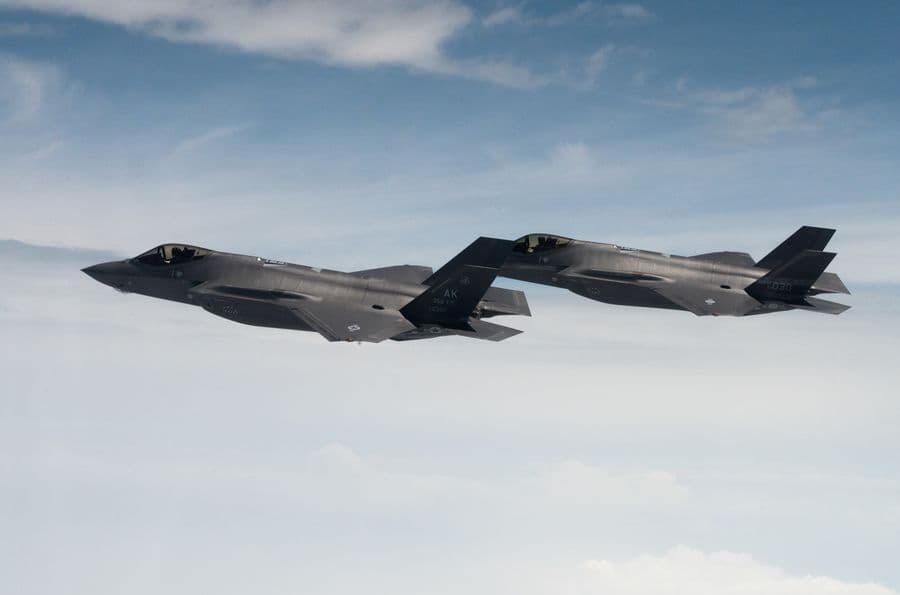
But U.S. providers also face a more capable set of domestic and global competitors across European, Middle East, and Asian defense markets. The European defense industrial landscape has been emboldened by new national and EU funding mechanisms such as the Security Action for Europe (SAFE) and the European Defense Industry Program (EDIP). Unburdened by extensive export controls, Israeli and South Korean firms have made notable inroads into Europe and beyond, while European firms have a growing foothold in Asia-Pacific. Japan, among the most dependable of U.S. defense equipment importers, is pursuing a fifth-generation fighter aircraft through co-development with Italy and the United Kingdom as part of the Global Combat Air Program (GCAP).
Reforms to the Rescue
These external developments coincide with the Trump Administration’s structural reforms to the export process. Mimicking its emphasis on speed in the domestic procurement process, a new more permissive approach to export licensing has injected new dynamism into the defense export process. Within the Pentagon, a long-overdue realignment of the Defense Security Cooperation Agency (DSCA) from the office of the Under Secretary of War for Policy to the Under Secretary of War for Acquisition and Sustainment organization has further supported these developments by better recognizing the impact exports have on U.S. acquisition. This organizational change marks a shift in the DOW’s approach to foreign sales from a defense cooperation mission to a more export-focused process.
Furthermore, President Trump’s February 2026 executive order (EO), “America First Arms Transfer Strategy,” explicitly connects defense exports to the health of the U.S. defense industry and calls for federal agencies to streamline the export process. The EO includes a dedicated task force to promote U.S. military sales and instructs the Departments of War and Commerce to find ways to simplify end-use monitoring, third-party transfers, and the Congressional notification process — complex processes that have long stymied defense exports.
Alliances & Defense Exports: Not a Marriage of Convenience
While U.S. defense exports are poised to benefit from a trifecta of strengths: combat-proven offerings, surging demand and funding, and a reformed U.S. government process — the Administration’s broader approach to alliances and partners could impede progress. Inconsistent and unpredictable engagement with allies, a penchant for holding allies responsible for domestic problems, and a transactional view of the defense trade are obstacles to increasing U.S. defense exports.
While the Trump Administration is committed to improving process and policy, the “America First Arms Transfer Strategy” retains hints of paternalism common in past administrations. The EO implies that the defense export process has been shaped by foreign customer priorities. It suggests that U.S. domestic defense industrial ills, including cost overrun and delivery delays, are the result of defense exports rather than a broken domestic funding and procurement process. Experience, however, suggests the opposite: U.S. approval processes and heavy-handed U.S. guidance on buying were the weakest links in U.S. arms sales and the most common complaint voiced by foreign customers. At the same time, needless disputes with our European allies over Greenland or needling our Canadian neighbors undermines historically deep and lucrative defense export markets.
Absent a more pragmatic relationship with Washington, the Danes will be less inclined to spend money on U.S. kit in the future. Similarly, signals from Ottawa about cuts to Canada’s planned F-35 procurement could be waved off, but brash U.S. policy can provide a convenient domestic political excuse to sideline major defense acquisitions. This risk is evident in Spain and Switzerland, which respectively stepped away from the F-35 offering or are seeking to limit its fleet size.
Taiwan’s massive $11 billion U.S. arms purchase could also be impacted. Lack of procedural movement has been attributed to the Administration’s prioritization of trade talks with China and a successful summit between presidents Trump and Xi Jinping this spring. However, any wavering in this U.S. commitment to this defense package could negatively affect contentious internal Taiwanese deliberations on Taipei’s broader $40 billion defense spending increase, a cornerstone of the Trump Administration’s demand that allies spend more on their own defense.
Supercharging Defense Exports
How can the Administration frame its thinking and avoid these pitfalls while safeguarding the progress it has made in reforming and growing defense exports? First, it should approach defense exports as a long-term decision driven by years of follow-on sustainment and modernization, rather than a one-off transaction. Officials must bear in mind that interoperability, a critical driver for buying U.S. equipment, matters — but only if the U.S. is perceived as a true and enduring ally. Furthermore, the customer is (almost) always right. The legacy of aggressively telling countries that they should buy, regardless of whether it is motivated by national security or U.S. defense industrial health, must be carefully messaged. Finally, the Administration should do its utmost to safeguard U.S. incumbency. Once lost, it will be harder for U.S. defense industry to win back customers.
Defense exports underpin the U.S. defense industry and have a vital role in sustaining critical DOW capability and systems. These economies of scale make U.S. acquisitions and trailing sustainment more affordable. Indeed, exports and the interoperability they enable are at the foundation of U.S. national security. Near-term U.S. export successes are not necessarily a reflection of long-term business dominance—countries may be busy shopping for U.S. defense kit today while they are pressing local industry to develop and build replacements for the medium- and long-term. Overly aggressive brinksmanship will have diminishing returns and push customers elsewhere. And most importantly, the health of the U.S. defense trade reflects the vitality of American alliances. U.S. kit is typically gold-plated and complex to operate and sustain. Stripped of alliances and the presumption of enduring support, U.S. defense solutions will increasingly appear less appealing compared to lower-cost and less capable international competitive offerings. U.S. industry and national security could pay the price.
Aleksandar (Alek) Jovovic is Deputy Director at the Center for the Industrial Base (CIB) and a Senior Fellow in the Defense and Security Department at the Center for Strategic and International Studies (CSIS) in Washington, DC.
In Pursuit of Nuclear Abolition
By Peter Huessy • RealClearDefense
Innovation Alone Won’t Prepare the U.S. for the Future Battlefield
By Joshua Segal • RealClearDefense
The sUAS Tactical Trifecta
By Bryan T. Woody • RealClearDefense
The Revolutionary War: When Strategic Options Share the Same Weakness
By Henry Yep • RealClearDefense
The Houthis Are Testing the Limits of Collective Defense
By Saima Afzal • RealClearDefense
Who Shoots Down the Drone Over the Shipyard?
By John Ferrari & Dillon Prochnicki • RealClearDefense
Northrop Grumman Breaks Out the Big Guns at AUSA
By Daniel Terrill, Defense News
Army Pursuing Diverse Array of New Anti-Air Interceptors
By Trevithick, The WarZoneWho Shoots Down the Drone Over the Shipyard?
By John Ferrari & Dillon Prochnicki, RCD
F-35C Lands for the First Time on a Ford-Class Aircraft Carrier
By The Aviationist