Prediction Markets Are Becoming a New Frontline for Military Operational Security
Published Nov. 16, 2026 • Read time: 9m
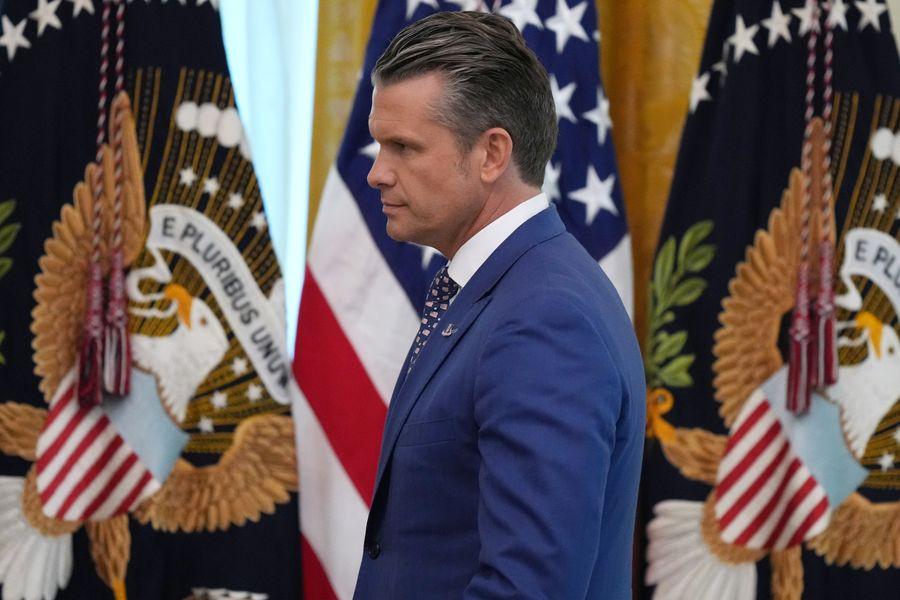
On October 20, 2026, U.S. Secretary of Defense Pete Hegseth signed a new directive prohibiting Department of Defense personnel from using non-public government information to place bets on prediction markets for military operations and related events. This policy was prompted in large part by allegations that Gannon Ken Van Dyke, a U.S. Army Special Forces Sergeant Major, used classified information to place bets on prediction markets related to the capture of Venezuelan President Nicolás Maduro, and the policy has extended to update military secrecy protocols and the handling of sensitive information.
The ban represents a necessary step toward safeguarding military operational security (OPSEC). “When an American Service member, intelligence professional, or other Department civilian engages in a financial transaction on a military outcome, they create a signal,” Hegseth said, according to media reports. In practice, the indirect transmission of sensitive information through financial transactions could provide an adversary with valuable intelligence. Adversaries may pay particular attention to such signals, as trading activity can offer clues about military operations that have not yet been publicly disclosed. Yet while the directive is an important first step to enforce internal discipline, personnel bans alone cannot neutralize the operational security risks of prediction markets without broader platform and contract regulation.
Market Signals as an Operational Security Vulnerability
If individuals with access to sensitive information place bets before a military operation goes public, the timing, size, and direction of their trades may expose critical clues to outside observers. Adversary intelligence agencies could combine these market signals with public news reports and diplomatic developments to infer when and where military operations will take place. Consequently, military personnel, intelligence professionals, and civilian staff across the Department of Defense are all subject to this directive. While the policy specifically cites Polymarket and Kalshi as examples, its restrictions are not limited to these two platforms. In August 2026, the Anti-Corruption Data Collective (ACDC), an anti-corruption research organization, reportedly found that among the accounts it analyzed on Polymarket, 152 had engaged in suspicious trading across military- and defense-related markets. These accounts were reportedly around 97.2% successful in their bets and made about $8 million in profit. Such trading patterns suggest the possible use of non-public information. Although these patterns alone do not prove that the account holders had access to classified information or were members of the military, the risk of sensitive information being compromised via prediction markets cannot be ruled out. The national security implications of this growing link between prediction markets and military operations should not be ignored.
As early as 2023, the U.S. Government Accountability Office (GAO) highlighted the need to strengthen risk management in the military information environment. Its report, Contested Information Environment: Actions Needed to Strengthen Education and Training for DOD Leaders, examined the challenges posed by social media, information technology, and other factors that shape how information is generated, disseminated, assessed for credibility, and used. These challenges illustrate how national security risks can emerge not only from direct disclosures of classified information, but also from the wider information environment in which seemingly unrelated signals acquire operational significance. Earlier cases also demonstrate that indirect information leaks are not a new phenomenon. Around 2011, incidents had already emerged in which social media exposed information about military movements and routes. This suggests that the risks associated with indirect disclosures have grown increasingly acute as digital platforms and information networks have expanded. Moreover, betting based on non-public information raises serious concerns regarding conflicts of interest, professional ethics, and market integrity. Prediction markets are designed to aggregate participants' independent assessments of future events based on public news and policy developments. However, when certain participants possess knowledge of unannounced military plans, a severe information asymmetry arises, distorting market outcomes through privileged access to government secrets rather than independent analysis.
Competing Approaches: Targeting Traders vs. Restricting Markets
Debate over the Pentagon’s new policy has increasingly expanded to the broader security risks posed by military-related prediction markets themselves. The Pentagon has emphasized that trading activity could generate signals for foreign intelligence agencies to exploit, while creating conflicts between individuals’ financial interests and their military duties. Meanwhile, oversight organizations such as the Project On Government Oversight (POGO) have advocated further restrictions on event contracts tied to military operations, and the ACDC’s analysis of Polymarket trading data has focused on how suspicious accounts may broadcast operational signals. Together, these perspectives point to two competing approaches in current policy discussions.
The first approach emphasizes restricting individuals who possess non-public information. Under this model, authorities target misconduct precisely by establishing clear trading prohibitions for military personnel, intelligence professionals, and Department of Defense employees. This clarifies individual responsibility and directly addresses conflicts of interest and the misuse of classified information, while avoiding sweeping restrictions on the broader market.
The second approach seeks to strengthen the regulation of high-risk markets and increase the responsibilities of prediction-market platforms. Given the high stakes for national security, authorities cannot rely solely on voluntary compliance by individual traders. If suspicious trading enables an adversary to anticipate the timing and location of a military operation, the resulting harm to troops cannot be undone by prosecuting traders after the fact. Proponents of this view argue that certain high-risk event contracts should be restricted or prohibited altogether before leaks can occur. This approach has gained traction in U.S. policy circles: in March 2026, Senators John Hickenlooper and Jack Reed wrote to the Commodity Futures Trading Commission (CFTC), calling for a ban on event contracts tied to U.S. military operations.
Legal Frameworks and Their Limitations
Existing U.S. laws already address several aspects of unauthorized disclosure and financial misconduct. However, the current legal framework is not fully equipped to manage the unique operational security risks posed by prediction markets.
● The Uniform Code of Military Justice (UCMJ, 10 U.S.C. §§ 892, 934) can be used to hold service members accountable for violating lawful orders, dereliction of duty, or other conduct covered by applicable provisions. However, it primarily operates within the military justice system and does not independently cover all civilian defense employees, platforms, or market participants.
● The Espionage Act and related national security laws (18 U.S.C. § 793) can impose liability for the unlawful handling, disclosure, or transmission of national defense information when the relevant statutory requirements are met. Yet whether trading activity that indirectly signals sensitive information constitutes a relevant offense remains a legal question. Not every bet based on inside information automatically constitutes espionage.
● Federal fraud and related criminal laws (18 U.S.C. § 1343; 7 U.S.C. § 6c(a)(6)) can be used to prosecute fraud or other unlawful conduct when the evidence satisfies the applicable statutory requirements. However, prosecutors must establish the specific elements of an offense. Unusual trading patterns or substantial profits alone do not establish criminal liability.
● The Commodity Exchange Act and CFTC oversight (7 U.S.C. § 7a-2(c)(5)(C); 17 C.F.R. § 40.11) provide a regulatory framework for covered derivatives markets, including market surveillance and measures to prevent manipulation and disorderly trading. Yet regulatory priorities do not fully align with military operational security. Coverage varies across platforms, and offshore markets pose additional jurisdictional challenges.
Consequently, the Pentagon's ban alone does not resolve the broader national security risks posed by prediction markets. Because the directive primarily targets the conduct of government personnel, it establishes clear boundaries for acceptable behavior but cannot, by itself, eliminate the underlying structural vulnerabilities.
Enforcement Challenges and the Offshore Loophole
Reports by the Associated Press and other major news organizations have focused on restrictions governing personnel conduct without detailing the directive’s enforcement mechanisms. Although Gannon Ken Van Dyke has faced criminal charges, the specific monitoring and compliance procedures backing the Pentagon’s new restrictions have not been fully disclosed. Practical implementation—including how compliance will be audited and how violations will be detected—therefore remains a critical open question.
At present, identifying suspicious trading generally involves tracking accounts and financial flows, cross-referencing abnormal trading signals with publicly available information, and relying on platforms’ internal surveillance and reporting mechanisms. However, these methods have limitations: unusual trading patterns do not definitively prove access to classified information, and sophisticated traders can conceal their identities or distribute their activity across multiple accounts and platforms.
A Reuters report published on October 22, 2026, noted that Polymarket and Kalshi were facing state-level lawsuits and federal scrutiny. This broader regulatory context suggests that policy discussions are extending beyond individual traders’ conduct toward the responsibilities of prediction-market platforms themselves. The central challenge is how to build a preventive system capable of mitigating national security risks before sensitive operational signals are broadcast, rather than merely punishing individuals after a leak has occurred.
Restricting platforms or specific categories of contracts offers a more fundamental way to address these risks at their source, yet doing so requires a more comprehensive regulatory framework. Kalshi and Polymarket differ significantly in their legal status and operating structures within the U.S. regulatory system. Restricting a domestic platform operating under CFTC oversight presents a very different legal challenge from attempting to control trading on an offshore platform operating beyond the direct reach of U.S. authorities.
For instance, Section 326 of the USA PATRIOT Act (31 U.S.C. § 5318(l)) requires financial institutions to implement a Customer Identification Program (CIP) and use reasonable, practicable measures to verify the identity of customers opening accounts, typically collecting names, dates of birth, addresses, and identification numbers. While U.S.-regulated operators can be required to enforce strict identity verification and block prohibited personnel from trading, these requirements are difficult to enforce against foreign platforms operating outside U.S. jurisdiction, leaving a significant regulatory loophole.
Ultimately, while the Pentagon's directive prohibiting the use of non-public government information for financial gain is an important step toward strengthening military operational security, internal personnel bans alone will not solve the root problem. Addressing the national security risks of prediction markets requires updating relevant legal frameworks (such as enforcing CFTC Rule 40.11 restrictions on military event contracts), strengthening investigative and cross-agency surveillance mechanisms between defense and financial regulators (including integrating prediction-market disclosures into security clearance vetting), and establishing clear rules for platform accountability (particularly anti-money laundering and identity-verification enforcement for offshore operators)—ensuring that sensitive military operations are protected before market signals can compromise them.
Yang Yunke is an independent researcher focusing on international security and technology governance. The author declares no relevant conflicts of interest.
End the Jones Act Waiver
By Mark H. Buzby • RealClearDefense
Prediction Markets Are Becoming a New Frontline for Military Operational Security
By Yang Yunke • RealClearDefense
Can Robots Bring Maneuver Warfare Back?
By Ayeza Areej • RealClearDefense
Buy Smarter, Fly More
By Jeff Kojac • RealClearDefense
Stop Gutting the Conventional Army
By R.D. Hooker, Jr. • RealClearDefense
Hung Cao Facing Contentious Confirmation To Become Navy Secretary
By Konstantin Toropin • Associated Press
U.S. Marines Expand M27 Rifle Contract
By Inder Singh Bisht
Kadena AFB Gets First F-15EX Eagle IIs
By Emily Ryan Miller, Defence BlogHung Cao Facing Contentious Confirmation To Become Navy Secretary
By AP
Fair Winds, Peacoat and Desert Camo: Navy Makes Big Changes to Seabag
By MTimes